Understanding UK VAT rates is essential because the rate you charge depends on the type of goods or services you supply. The UK currently operates three main VAT rates: 20%, 5%, and 0%. Each rate applies to specific categories defined under UK VAT legislation.
The standard rate of VAT increased from 17.5% to 20% on 4 January 2011, and it remains at 20% today.
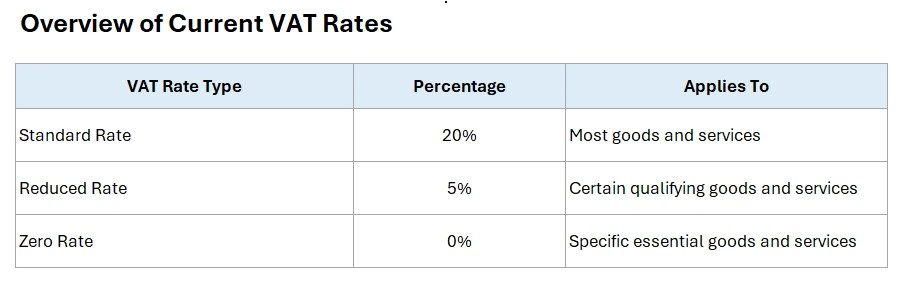
The rate a business must charge depends on the nature of the supply, not the type of business. Know More About VAT via the Official Government Website and calculate VAT.
Standard Rate – 20%
The standard rate of 20% applies to most goods and services supplied in the UK. If a supply does not fall within a reduced or zero-rated category, it is generally standard-rated.
Typical supplies include:
- General retail goods
- Professional and consultancy services
- Most construction services
- Electronics and equipment
This is the default rate applied across the majority of commercial transactions.
Reduced Rate – 5%
The reduced rate of 5% applies only to specific categories set out in legislation. It does not apply broadly and must meet qualifying conditions.
Common examples include:
- Children’s car seats
- Domestic fuel and power
- Certain energy-saving materials
- Some residential property conversions
The reduced rate exists to support essential or socially important goods and services.
Zero Rate – 0%
Zero-rated supplies are taxable supplies charged at 0%. Although VAT is charged at 0%, these supplies remain within the VAT system.
Common zero-rated goods include:
- Most food items
- Children’s clothing and footwear
- Books and newspapers
Zero-rated sales still count toward the VAT registration threshold.
VAT-Exempt Supplies
Some goods and services are exempt from VAT. Exempt supplies fall outside the taxable VAT system.
Examples include:
- Postage stamps
- Many financial services
- Insurance
- Certain property transactions
- Qualifying education and healthcare services
If a business makes only exempt supplies, it generally cannot charge VAT or reclaim input VAT.